Under $1,000 tier
What car insurance costs in Wyoming
Wyoming's average premium next to the U.S. figure, the one line where the state runs far above average, and the rules and tools behind the price.
By Guardbrook Editorial Team Updated 6 min read
At a glance
- Average yearly spend, 2023
- $948
- Change from 2022
- +12%
- Minimum liability limits
- 25/50/20
- Uninsured drivers, 2023
- 6.7%
Bottom line
Wyoming drivers spent an average of $948 per insured car in 2023, about 26% below the U.S. average of $1,282, and a car with all three main coverages averaged $1,180. Liability is cheap here, but comprehensive averaged $452, nearly twice the national figure and more than the average liability premium. The financial responsibility minimum is 25/50/20, and uninsured motorist coverage comes with a policy unless you reject it.
The Wyoming bill, line by line
Guardbrook
Average car insurance bill, 2023
Wyoming
Liability$390
Collision$338
Comprehensive$452
Full coverage$1,180
Average spend per car$948
Compared with the U.S.−26%
Uninsured drivers6.7%
Average yearly premiums per insured car (NAIC); uninsured share: Insurance Research Council estimate. Averages, not a quote. Where these numbers come from
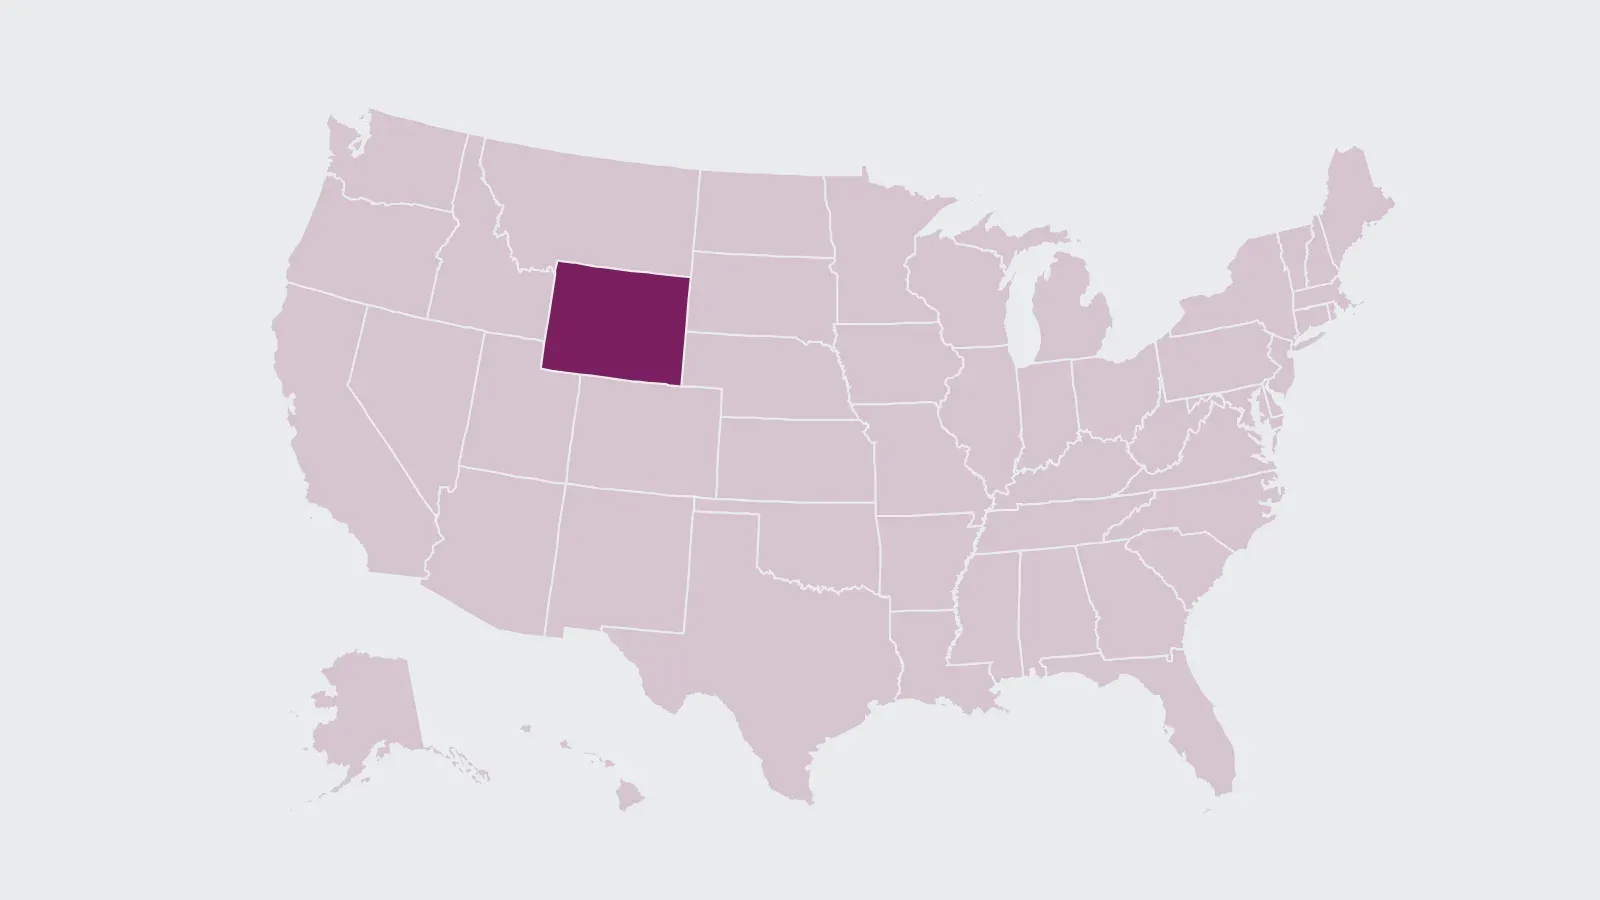
Price tier on the map
Under $1,000 a year
- Minimum liability limits
- 25/50/20
- Uninsured motorist coverage included at minimum bodily injury limits unless the named insured rejects it
- Credit-based insurance scores
- Allowed, not as the sole basis to deny or cancel
- W.S. 26-2-134 (2003 Wyo. Sess. Laws ch. 102): used only with other factors; notice when used and when adverse
- Regulator
- Wyoming Department of Insurance
Wyoming's bill, line by line
The National Association of Insurance Commissioners (NAIC) reports what insurers collected in each state. For 2023, its latest year by state, Wyoming's average expenditure was $948 per insured car, up 12% from $848 in 2022. That average includes cars with liability only. A car with liability, collision and comprehensive had a combined average premium of $1,180.
| Coverage | Wyoming | United States |
|---|---|---|
| Liability | $390 | $737 |
| Collision | $338 | $464 |
| Comprehensive | $452 | $238 |
| All three (combined premium) | $1,180 | $1,438 |
| Average expenditure | $948 | $1,282 |
Two lines pull in opposite directions. Liability, at $390, is about 47% below the national average, and collision is about 27% lower. Comprehensive, at $452, is about 90% higher, and in Wyoming it is the largest of the three coverages. Comprehensive pays for damage other than a collision, so a driver who drops it saves more than the national average would suggest, but also takes on more risk. Where the car is kept matters too; see how location sets a price.
Wyoming's coverage minimums
Wyoming's financial responsibility law sets the minimum at $25,000 for bodily injury or death of one person, $50,000 for two or more people and $20,000 for damage to other people's property in one accident.
- Uninsured motorist coverage must be included in any policy covering bodily injury liability for a car registered or principally garaged in Wyoming, at the state's minimum bodily injury limits.
- You can turn it down. The named insured may reject uninsured motorist coverage. Once rejected, the insurer need not add it at renewal unless you ask for it in writing.
- Collision and comprehensive are your choice under state law, though a lender will expect both on a financed car.
The Insurance Research Council estimated that 6.7% of Wyoming drivers were uninsured in 2023, among the lowest shares in the country. Keeping uninsured motorist coverage still protects you against the drivers who aren't covered; our page on limits and deductibles explains how to set it.
How Wyoming handles rates
Wyoming's rating law presumes a competitive market. Where a market is competitive, insurers must keep their rates and supporting information on file and hand them over when the Insurance Commissioner asks. Only in a market found noncompetitive must an insurer file rates at least 30 days before they take effect. The commissioner can still disapprove rates under the state's rating standards.
Credit can count, within limits. A 2003 law, W.S. 26-2-134, has the Insurance Commissioner set rules for credit scoring in personal auto and homeowners policies: credit can't be the sole basis to cancel, deny or nonrenew a policy, it may be used only with other underwriting factors that don't depend on credit, and the insurer must tell you when it uses credit and when the result works against you. If your credit raises your price, ask the insurer for the reasons in writing and contact the Department of Insurance's Consumer Affairs section. More on credit-based insurance scores.
Coverage for hard-to-insure drivers
A driver no company will take can get coverage through the Western Association of Automobile Insurance Plans, which the Wyoming Department of Insurance lists for this purpose. An agent can submit the application. Expect higher prices than the regular market, and shop again as your record improves; our guide to assigned risk plans explains how these plans work.
Ways to pay less in Wyoming
- Use the department's shopping aids. The Wyoming Department of Insurance posts an Auto Insurance Shopping Tool and a guide to usage-based insurance on its consumer page, along with links to NAIC auto guides.
- Price comprehensive carefully. Since it is the costliest line on an average Wyoming bill, compare a higher comprehensive deductible across insurers before you decide to drop the coverage.
- Check the break-even point. The deductible break-even calculator shows how many claim-free years a higher deductible needs to pay off.
- Get help from Consumer Affairs. File a complaint through the department's online portal, or call 307-777-7402 or toll-free 800-438-5768.
Questions drivers ask
Why is comprehensive coverage so expensive in Wyoming?
The NAIC data show the cost, not the cause: Wyoming's 2023 comprehensive average was $452 against $238 nationally, and higher than the state's $390 average liability premium.
What is the minimum car insurance in Wyoming?
Liability of $25,000 per person, $50,000 per accident and $20,000 for property damage (25/50/20). Uninsured motorist coverage is included unless the named insured rejects it.
Is car insurance cheaper in Wyoming than the national average?
On average, yes. NAIC data for 2023 put Wyoming's average expenditure at $948 per insured car against $1,282 nationally, and the full-coverage combined premium at $1,180 against $1,438.
Where do Wyoming drivers go if no insurer will cover them?
The Western Association of Automobile Insurance Plans, listed by the Wyoming Department of Insurance. See assigned risk plans.
Where the figures come from
- NAIC — Auto Insurance Database Report 2022/2023 (state average premiums and expenditures)
- Wyoming Legislature — 2003 SF0081 (enrolled act creating W.S. 26-2-134, limiting the use of credit scoring)
- Wyoming Department of Insurance — Consumers
- Wyoming Statutes § 31-9-102 — Proof of financial responsibility (Justia)
- Wyoming Statutes § 31-10-101 — Uninsured motorist coverage (Justia)
- Wyoming Statutes Title 26, Chapter 14 — Rates and rating organizations (Justia)
- Insurance Information Institute — Uninsured motorists (Insurance Research Council estimates)
Facts on this page were checked against these sources on October 26, 2026. NAIC averages are for 2023, the latest year the NAIC has published by state.
Have your rate shopped
Averages can't price your car and your record. Tell us the basics of your policy and Guardbrook passes them to licensed insurance agents and insurers who can quote it; you decide whether to switch.
- 1 Your cars, drivers and current policy.
- 2 How agents can reach you, and your consent.
- 3 A licensed insurance agent or insurer contacts you with quotes. Your policy stays as it is until you decide to switch.
Guardbrook is not an insurance company or agency and doesn't sell, quote or bind policies. You pay Guardbrook nothing; the licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Read next
-
Price factor
Annual mileage
One of three rating factors named in California law, and a common discount elsewhere. How miles are checked.
-
Way to save
Pay-per-mile insurance
$45 plus 6¢ a mile is $93 at 800 miles vs. a $150 policy; it breaks even at 1,750 miles a month.
-
Shopping guide
Reading your declarations page
Drivers, cars, limits such as 50/100/50, deductibles, rejected coverages, required discounts and the premium.