$1,500 or more tier
What car insurance costs in Rhode Island
Why the average Rhode Island bill tops the national one, what state law adds to every policy, and where you still have room to cut.
By Guardbrook Editorial Team Updated 6 min read
At a glance
- Average yearly spend, 2023
- $1,539
- Change from 2022
- +8%
- Minimum liability limits
- 25/50/25
- Uninsured drivers, 2023
- 12.4%
Bottom line
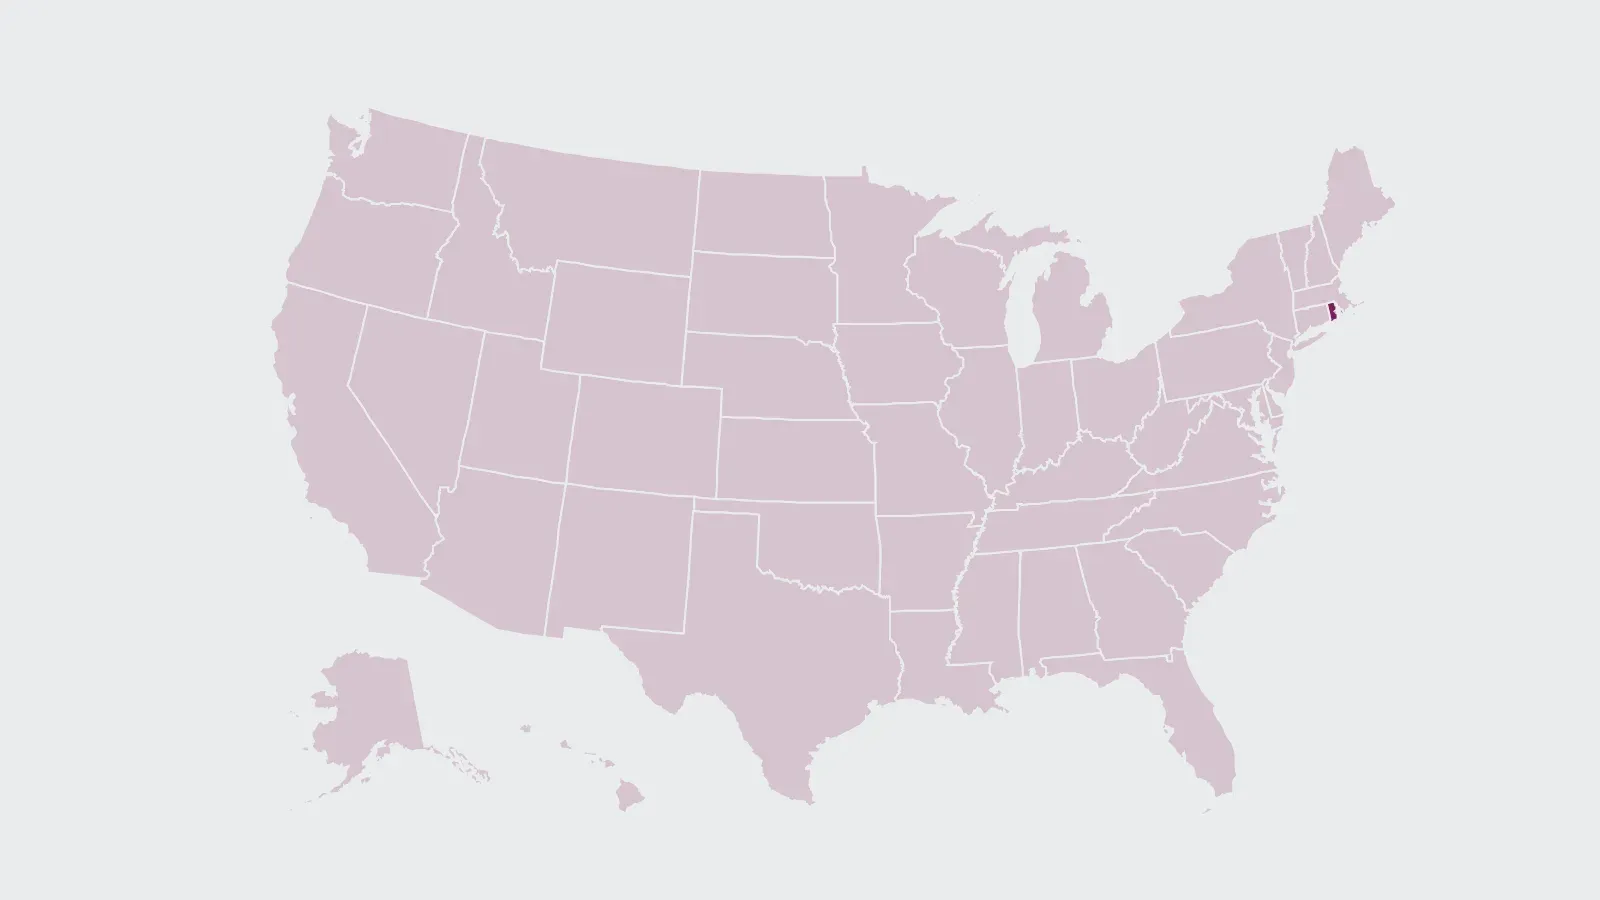
Rhode Island drivers spent an average of $1,539 per insured car in 2023, about 20% more than the U.S. average of $1,282, and a fully covered car averaged $1,710. Liability is the line that runs high. The state requires 25/50/25 liability, and every policy includes uninsured motorist coverage unless you lower it in writing. Rhode Island also makes insurers that use credit scores grant exceptions for serious life events.
The Rhode Island bill, line by line
Guardbrook
Average car insurance bill, 2023
Rhode Island
Liability$984
Collision$540
Comprehensive$186
Full coverage$1,710
Average spend per car$1,539
Compared with the U.S.+20%
Uninsured drivers12.4%
Average yearly premiums per insured car (NAIC); uninsured share: Insurance Research Council estimate. Averages, not a quote. Where these numbers come from
Price tier on the map
$1,500 or more a year
- Minimum liability limits
- 25/50/25 (or $75,000 combined single limit)
- Uninsured motorist coverage included at liability limits unless lowered in writing (R.I. Gen. Laws § 27-7-2.1)
- Credit-based insurance scores
- Allowed, with life-event exceptions
- 230-RICR-20-05-15: reasonable exceptions on written request for divorce, illness, job loss and other listed events
- Regulator
- Rhode Island Department of Business Regulation, Insurance Division
Rhode Island's bill, line by line
The National Association of Insurance Commissioners (NAIC) publishes what insurers collected per insured car in each state. For 2023, its most recent state year, Rhode Island's average expenditure was $1,539. That was 8% more than the $1,423 of 2022, a smaller increase than the 14% for the country. The figure averages liability-only and fully covered cars; with liability, collision and comprehensive on one car, the combined premium was $1,710.
| Coverage | Rhode Island | United States |
|---|---|---|
| Liability | $984 | $737 |
| Collision | $540 | $464 |
| Comprehensive | $186 | $238 |
| All three (combined premium) | $1,710 | $1,438 |
| Average expenditure | $1,539 | $1,282 |
Liability does most of the work: at $984, it was about a third higher than the national $737. Collision was also above the U.S. figure, by $76, while comprehensive was $52 below it. Since liability is the part you can't drop, a Rhode Island driver has less room to cut by removing coverage and more reason to compare what different companies charge for the same limits. Our guide to comparing quotes line by line shows how to line them up.
Coverage Rhode Island requires
A Rhode Island owner's liability policy must cover at least $25,000 for injury or death of one person, $50,000 for two or more people in one accident and $25,000 for damage to others' property. State law also accepts a $75,000 combined single limit in place of the three separate amounts.
- Uninsured motorist coverage comes with every policy, by default at the same limits as your bodily injury liability. You can choose a lower limit in writing, but not below the state minimum.
- Buying only the minimum? Then you may reduce uninsured motorist coverage to zero, but only after signing a notice, approved by the state, that warns about the risks of uninsured and underinsured drivers.
- Uninsured motorist property damage can be rejected in writing, and you don't need it if you carry collision coverage.
The Insurance Research Council estimates that 12.4% of Rhode Island drivers were uninsured in 2023, a bit below the U.S. rate of 15.4%. Your insurer must tell you about the coverage and optional limits at renewal, so that is a natural moment to revisit them. Our page on limits and deductibles explains the trade-offs.
Credit scores and life events in Rhode Island
Rhode Island lets insurers use insurance scores, which are built partly from credit history, in pricing car insurance, but a state regulation (230-RICR-20-05-15) adds protections. If an extraordinary life event directly hurt your credit, an insurer that uses scores must, at your written request, make a reasonable exception. The events listed include:
- a catastrophic event, or a serious illness or injury
- the death of a close family member, or a divorce
- identity theft, or an involuntary job loss lasting three months or more
- overseas military deployment
The insurer may ask for documents and may require the request within 60 days of the application or renewal. It must tell you about this exception when a score has hurt your rating. If you have little or no credit history, the insurer may treat you as average, set the score aside or follow its filed rules. See how credit-based scores affect premiums.
Coverage when insurers turn you down
Drivers who can't get insurance in the regular market can apply to the Rhode Island Automobile Insurance Plan, the state's assigned risk plan. Every insurer writing car insurance in the state must help fund it. Plan policies are issued for one year on forms approved by the Department of Business Regulation, and the plan files its own rates with the department. Our guide to assigned risk plans explains how to apply through an agent.
Paying less in Rhode Island
- Compare the liability line first. It is the costliest part of the average Rhode Island bill, so price the same limits with two or three companies.
- Ask about a credit exception in writing if a divorce, illness, job loss or another listed event damaged your credit, ideally within 60 days of applying or renewing.
- Revisit your deductibles. The deductible break-even calculator shows how long a higher one takes to pay off.
- Contact the Insurance Division of the Department of Business Regulation at (401) 462-9520, 8:30 a.m. to 4 p.m. Eastern on weekdays, or file a complaint online if your insurer won't resolve a problem.
Questions drivers ask
Why is car insurance in Rhode Island more expensive than average?
The NAIC's 2023 figures show liability as the main difference: $984 per insured car in Rhode Island against $737 nationally. The NAIC numbers show where the cost sits, not why.
What is the minimum car insurance in Rhode Island?
Liability of $25,000 per person, $50,000 per accident and $25,000 for property damage, or a $75,000 combined single limit. Uninsured motorist coverage is included unless you lower it in writing.
Can I drop uninsured motorist coverage in Rhode Island?
Only if you buy the minimum liability limits, and only after signing a state-approved notice about the risks. Otherwise you can lower it in writing, but not below the state minimum.
What if a divorce or job loss hurt my credit?
Rhode Island requires insurers that use insurance scores to make reasonable exceptions, on written request, for listed life events such as divorce, a death in the family, serious illness or an involuntary job loss. See credit-based insurance scores.
Where the figures come from
- NAIC — Auto Insurance Database Report 2022/2023 (state average premiums and expenditures)
- Rhode Island General Laws § 31-47-2 — Definitions (owner's liability policy minimum limits)
- Rhode Island General Laws § 27-7-2.1 — Uninsured motorist coverage
- 230-RICR-20-05-15 — Use of Credit: Extraordinary Life Events
- 230-RICR-20-05-8 — Rhode Island Automobile Insurance Plan
- Rhode Island Department of Business Regulation — Insurance Division
- U.S. Bureau of Labor Statistics — CPI, table 2 (motor vehicle insurance)
- Insurance Information Institute — Uninsured motorists (Insurance Research Council estimates)
Facts on this page were checked against these sources on October 26, 2026. NAIC averages are for 2023, the latest year the NAIC has published by state.
Have your rate shopped
Averages can't price your car and your record. Tell us the basics of your policy and Guardbrook passes them to licensed insurance agents and insurers who can quote it; you decide whether to switch.
- 1 Your cars, drivers and current policy.
- 2 How agents can reach you, and your consent.
- 3 A licensed insurance agent or insurer contacts you with quotes. Your policy stays as it is until you decide to switch.
Guardbrook is not an insurance company or agency and doesn't sell, quote or bind policies. You pay Guardbrook nothing; the licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Read next
-
Price factor
Credit-based insurance scores
Allowed in most states, barred from auto rates in CA, HI, MA and MI. Your rights when credit raises the price.
-
Shopping guide
Assigned-risk plans
Turned down twice in Texas or Maryland? How state plans place you, what they cover and how to get back out.
-
Price factor
Coverage limits and deductibles
What 25/50/25 means, why liability is about half of a $1,438 full-coverage bill, and how to size a deductible.