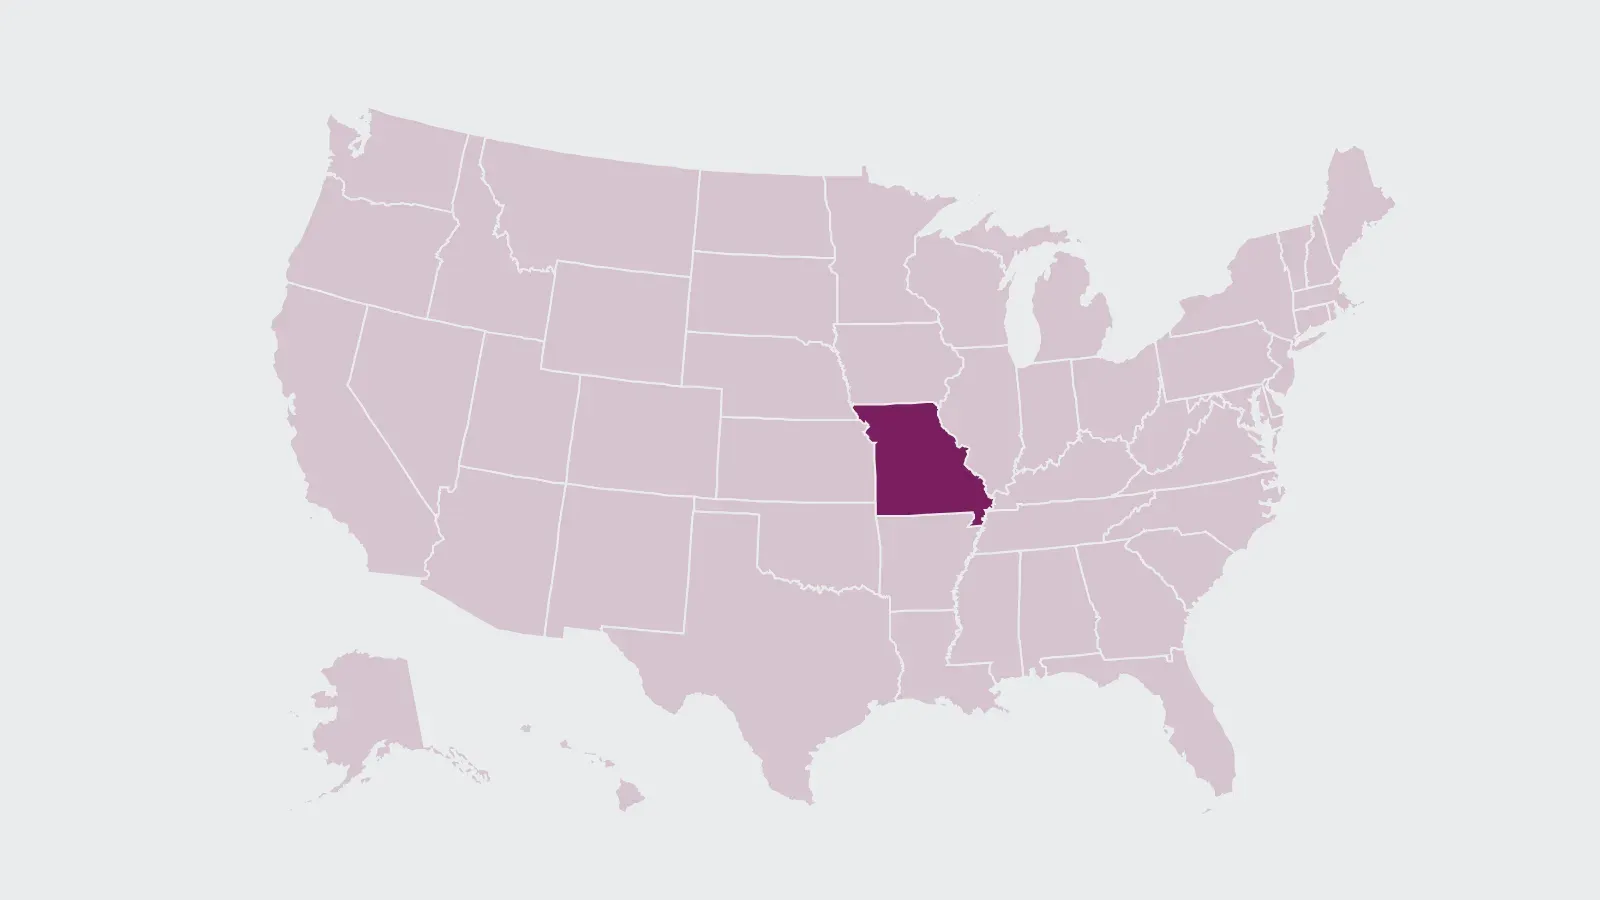
$1,000–$1,249 tier
What car insurance costs in Missouri
The 2023 Missouri bill against the U.S. average, the coverage state law requires, and the protections you have when credit affects your price.
By Guardbrook Editorial Team Updated 6 min read
At a glance
- Average yearly spend, 2023
- $1,155
- Change from 2022
- +15%
- Minimum liability limits
- 25/50/25
- Uninsured drivers, 2023
- 20.7%
Bottom line
Missouri drivers spent an average of $1,155 per insured car in 2023, about 10% below the U.S. average, and full coverage averaged $1,323. Every policy needs 25/50/25 liability and must include uninsured motorist coverage, which matters in a state where about one driver in five was uninsured in 2023. Insurers may weigh credit, but Missouri law gives you specific rights when it counts against you.
The Missouri bill, line by line
Guardbrook
Average car insurance bill, 2023
Missouri
Liability$614
Collision$400
Comprehensive$308
Full coverage$1,323
Average spend per car$1,155
Compared with the U.S.−10%
Uninsured drivers20.7%
Average yearly premiums per insured car (NAIC); uninsured share: Insurance Research Council estimate. Averages, not a quote. Where these numbers come from
Price tier on the map
$1,000 to $1,249 a year
- Minimum liability limits
- 25/50/25
- Uninsured motorist coverage must be included in every liability policy (RSMo 379.203)
- Credit-based insurance scores
- Allowed, not as the only factor
- RSMo 375.918: notice of adverse action, written reasons on request, re-underwriting after corrections
- Regulator
- Missouri Department of Commerce and Insurance
Missouri's average bill and the U.S. figure
The National Association of Insurance Commissioners (NAIC) reports what insurers collected per insured car, state by state. In 2023, the latest year with state figures, the Missouri average expenditure was $1,155. That was 15% more than the $1,004 recorded for 2022, slightly faster growth than the national average.
| Coverage | Missouri | United States |
|---|---|---|
| Liability | $614 | $737 |
| Collision | $400 | $464 |
| Comprehensive | $308 | $238 |
| All three (combined premium) | $1,323 | $1,438 |
| Average expenditure | $1,155 | $1,282 |
Liability and collision both came in below the national averages, by about 17% and 14%. Comprehensive, which pays for theft and damage that isn't a crash, ran about 29% higher at $308. The full-coverage premium ended up 8% under the U.S. figure. For your own car, the ZIP code, vehicle and driving record will matter far more than the state average; see how location sets a price.
Coverage required under Missouri law
The Missouri Department of Commerce and Insurance says you must insure your car for injuries you cause to others, with at least $25,000 per person, $50,000 per accident and $25,000 for property damage. The Department of Revenue checks that liability coverage stays in force, and a lapse can lead to a suspended registration and possibly a suspended driver's license.
- Uninsured motorist coverage must be included in every Missouri auto liability policy, at no less than the state's bodily injury minimums.
- Collision and comprehensive are your choice under state law, but a lender or lessor will normally require them.
- A gap in coverage can cost you later: the department notes that Missouri law doesn't stop an insurer from placing a driver in a high-risk policy after a 30-day lapse.
With about 20.7% of Missouri drivers uninsured in 2023, by the Insurance Research Council's estimate, the required uninsured motorist coverage does real work. Raising it above the minimum is one of the choices our page on limits and deductibles helps you weigh.
Who sets Missouri prices, and the credit rules
The Department of Commerce and Insurance does not set insurance rates. Each insurer's rates are based on the claims it pays, its operating expenses and its profit, so prices for the same driver can vary from company to company.
Credit can play a part, within limits set by section 375.918 of the Missouri statutes. An insurer must tell you at application that it may gather credit information. It can't take an adverse action on credit alone, without another factor unrelated to credit. If credit hurt your price, it must say so and tell you how to get a free credit report and dispute errors. You can ask for a written statement of reasons within 30 days and, after a correction, ask to be re-underwritten. On a renewal, credit can't be the basis for adverse action until the policy's third anniversary. More on credit-based insurance scores.
If you can't find coverage
Drivers who have trouble getting insurance from companies in the regular market may obtain coverage from the Missouri Automobile Insurance Plan. Ask a licensed agent how to apply and what the plan would charge next to any regular offer you can still get. Our guide to assigned risk plans walks through the process.
How to bring a Missouri premium down
- Shop with the same limits and deductibles. Missouri's regulator doesn't set rates, so the spread between companies can be wide.
- Check complaint records before you switch. The department's Complaint Index lists complaints against auto insurers doing business in Missouri.
- Ask about a multi-policy discount. Our page on bundling home and auto explains when it pays off.
- Call the department if something seems wrong. The consumer hotline is 800-726-7390, and complaints can also be filed online.
Questions drivers ask
What are Missouri's minimum car insurance requirements?
Liability of $25,000 per person and $50,000 per accident for injuries and $25,000 for property damage, plus uninsured motorist coverage, which every Missouri liability policy must include.
Is car insurance cheaper in Missouri than the national average?
On average, yes. NAIC data for 2023 put Missouri's average expenditure at $1,155 per insured car against $1,282 nationally, and full coverage at $1,323 against $1,438.
Can a Missouri insurer raise my rate because of my credit?
Credit can be a factor, but not the only one in an adverse decision. You must be told when credit hurt you, and you can ask for a written explanation and re-underwriting after a correction. See credit-based insurance scores.
What happens if my Missouri coverage lapses?
The Department of Revenue tracks coverage, and a lapse can lead to a suspended registration and possibly a suspended license. An insurer may also place you in a high-risk policy after a 30-day lapse.
Where the figures come from
- NAIC — Auto Insurance Database Report 2022/2023 (state average premiums and expenditures)
- Missouri Department of Commerce and Insurance — Automobile insurance
- Missouri Department of Commerce and Insurance — Consumer guide to automobile insurance
- Missouri Department of Commerce and Insurance — Auto insurance FAQs
- Missouri Revised Statutes § 375.918 — Use of credit information
- Missouri Revised Statutes § 379.203 — Uninsured motorist coverage
- Insurance Information Institute — Uninsured motorists (Insurance Research Council estimates)
Facts on this page were checked against these sources on October 26, 2026. NAIC averages are for 2023, the latest year the NAIC has published by state. The credit rules summarized here are those in section 375.918 for contracts entered into on or after July 1, 2003.
Have your rate shopped
Averages can't price your car and your record. Tell us the basics of your policy and Guardbrook passes them to licensed insurance agents and insurers who can quote it; you decide whether to switch.
- 1 Your cars, drivers and current policy.
- 2 How agents can reach you, and your consent.
- 3 A licensed insurance agent or insurer contacts you with quotes. Your policy stays as it is until you decide to switch.
Guardbrook is not an insurance company or agency and doesn't sell, quote or bind policies. You pay Guardbrook nothing; the licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Read next
-
Price factor
Credit-based insurance scores
Allowed in most states, barred from auto rates in CA, HI, MA and MI. Your rights when credit raises the price.
-
Way to save
Bundling home and auto
Wisconsin's regulator puts the package discount at up to 15%. Why a bundle can still cost more than two policies.
-
Shopping guide
Why your premium went up
Market-wide changes vs. your own record. The price index fell 5.0% to September 2026; yours may not have.